
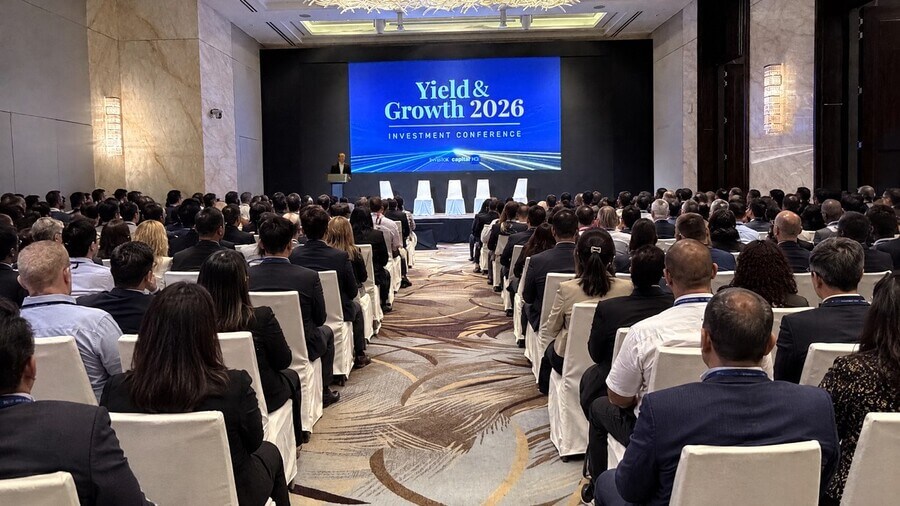
On 28 October, in a ballroom at The Westin Singapore, more than 350 private investors, family offices and professional allocators were reminded that a AAA rated Australian government bond now pays around 5.2 per cent a year. That is the bar every Bali villa should be measured against. Whether Bali can clear it is not really the question. Villas that beat it comfortably exist across the island, and they pay something no bond ever has. The real question is how a private investor sitting in Singapore finds them.
I attended Yield & Growth 2026, Wholesale Investor’s Australia to ASEAN investment conference, as an invited guest of its cofounder, Steve Torso. The day ran on two tracks: yield, covering private credit, real estate credit and listed income, and growth, covering private equity, venture and deep technology. The audience was Singapore and regional capital, and the mood was clear. After a decade of near zero rates, sophisticated investors have choices again, and they are asking harder questions of every asset in front of them.
A Room That Has Choices Again
One fixed income specialist on the morning panel made the point that stayed with me. For years, he said, private clients chased yield further up the risk curve, into assets whose risks they did not fully understand. Many of them mistook price stability for performance. A holding that never seemed to move in value felt safe, until the day its owner needed liquidity and discovered what it was really worth.
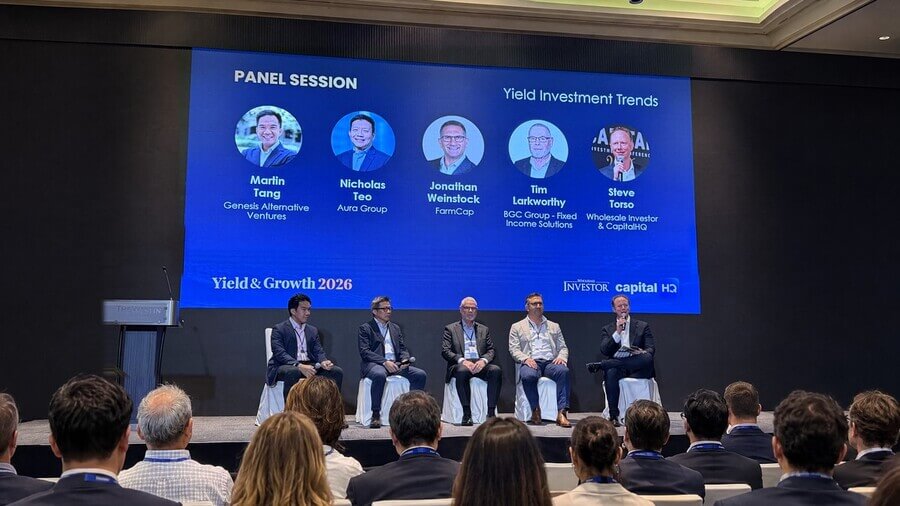
Bali property has been sold the same way for a decade, with headline yields and very little underneath them. For a Singapore investor, the 10 year Singapore government bond paid about 2.2 per cent at the end of October, while the Australian equivalent paid 5.21 per cent on the day of the conference. A villa in Canggu or Uluwatu is no longer competing with nothing. That is not a reason to stay away from Bali. It is a reason to stop buying the average and start buying the exception, and finding the exception is the only thing we do at Fullers Properties, where we act solely for the buyer.
What the Median Villa Actually Returns
REID, our independent market data partner, tracks daily rental performance across more than 44,000 properties on the island. For 2 and 3 bedroom leasehold villas over the 12 months to June 2026, its figures look like this.
The median is the villa in the exact middle. Line up every villa in an area from the weakest return to the strongest, and the median is the one halfway along: half earned more, half earned less. It is a fairer guide than a simple average, which a handful of exceptional or failing villas can pull up or down. The middle 50 per cent column goes one step further, showing the range that covers the typical half of the market once the best and worst quarters are set aside.
| Area | Median gross yield | Median net yield | Middle 50% of villas (net) | Share above 8% net |
|---|---|---|---|---|
| Uluwatu | 14.4% | 7.2% | 5.5% to 9.8% | 38% |
| Ubud | 13.4% | 6.7% | 4.9% to 8.8% | 29% |
| Canggu | 12.8% | 6.4% | 4.8% to 8.2% | 22% |
| Pererenan | 12.2% | 6.1% | 4.5% to 7.9% | 19% |
| Seminyak | 11.6% | 5.8% | 4.1% to 7.5% | 14% |
Source: REID, 12 months to June 2026. Net yield applies REID’s standard 50% operating cost assumption to gross revenue.
Even the median villa in every area on this list out earns the Australian bond on income. The gap between gross and net is where most marketing material goes quiet. Full service management typically takes 20 to 30 per cent of gross revenue. Booking platforms take another 12 to 15 per cent. Utilities and maintenance in a tropical climate absorb 8 to 12 per cent, and keeping a villa photogenic enough to hold its nightly rate costs a further 3 to 5 per cent. A sound investment case starts from the net figure, never the gross.
The Question Every Leasehold Buyer Should Ask
Leasehold is the part of the calculation that rarely makes the brochure. On a 26 year lease, if the villa’s value ran down evenly with the term, roughly 3.8 per cent of the purchase price would return to the owner each year as income rather than profit. Applied to the Canggu median, that leaves a true return closer to 2.6 per cent.
In practice, the best villas do not behave that way. Secured extension rights, land that keeps appreciating around the property and steady resale demand for well located villas all hold value up. Those protections are not assumptions to make after purchase. They are clauses to verify in writing before it, and they are a large part of the difference between a villa that compounds and one that quietly runs down.
Where the Average Hides the Opportunity
These are general market averages, and averages flatten the properties that matter. In our own work we have seen operating villas delivering proven net returns of 11 to 18 per cent and above. In every case the result came down to a small number of factors: a specific location within a corridor rather than the corridor’s name, a design that guests cannot find elsewhere, and operation that keeps occupancy and nightly rates in the top tier.
REID’s data points the same way. More than a third of Uluwatu villas cleared 8 per cent net last year. The villas that do so typically run above 72 per cent occupancy, or were bought at least 15 per cent below the local median price per square metre. That second condition is a buying decision, not a market condition. REID also finds that median asking prices in Canggu and Pererenan sit roughly 20 per cent above recent sold prices. The difference between an average outcome and a top quartile one is usually settled at the negotiating table, by the person sitting on the buyer’s side of it.
Selection also means reading supply. Uluwatu holds the strongest median yield on this list and added 747 villas to the rental pool in a single year, an increase of 33.4 per cent. Canggu grew by just 2.2 per cent. The opportunity is real, but it belongs to the buyer who knows which street, which design and which operator will still stand out in two years.
This is why investors come to us. Not to be convinced that Bali works, but to be shown precisely where it does. Good yielding homes and properties exist on this island in every price bracket. They are simply outnumbered by the average ones, and they are rarely the villas with the loudest marketing. Our work is to separate the two before a single dollar moves.
Who Is Already Buying
Serious capital rarely moves alone, and it is already moving here. Singapore was the largest source of foreign direct investment into Indonesia in the first quarter of 2026, at US$4.6 billion, according to Indonesia’s Ministry of Investment. In Bali, the 747 villas added to Uluwatu’s rental pool in a single year represent hundreds of investors who have already made their decision.
Our own desk tells the same story. Over the past year our mandates have included a Japanese private equity and development group assembling hotels, resorts and private villas, alongside private buyers from Australia, Dubai, the United Kingdom and Europe. Our conversations with family offices in Hong Kong and Singapore have moved from whether Bali belongs in a portfolio to which assets, in which structure, and how soon.
Family offices have always preferred to invest where their peers are investing, and for good reason. Shared conviction means shared scrutiny. That is the thinking behind Fullers Wealth Club, a community for private investors and family offices where members see the same verified properties, compare notes with people who have already bought, and benefit from the diligence of everyone in the room.
What the Numbers Cannot Buy
No bond has ever hosted a family for Christmas.
That sounds obvious, yet it is the line most investment comparisons leave out. Bali sits in the same time zone as Singapore, less than three hours away by air. A villa here is a place a family can reach after school on a Friday, a base for the parents who want to spend longer each year somewhere slower, and the house the children will remember long after they have forgotten what the portfolio returned in 2026.
One of our clients, a family business owner who bought through us last year, put it more simply than any spreadsheet could. “The rental income covers the villa,” he told me. “The villa covers everything I cannot put a number on.”
There is also a financial case for the lifestyle. The weeks a family spends in its own villa are weeks it is not paying for a resort, so the comparison with a bond is never quite like for like. One pays a coupon. The other pays a coupon, a holiday, a second home on one of Asia’s most loved islands and a real asset outside the investor’s home market. For family offices thinking in generations rather than quarters, that combination is difficult to find anywhere else in the region.
Reading a Yield the Way an Allocator Would
The investors in that Singapore ballroom would never accept a fund manager’s return figure without knowing the costs, the holding period and the exit. A villa deserves the same questions. Is the quoted figure gross or net, and net of what? Is it calculated on the price being asked or the price actually paid? How many years remain on the lease, and who carries the obligation to extend it? How many comparable villas will open within a kilometre in the next 18 months?
At Fullers Properties, these questions sit inside the Examine stage of our CLEAR Buyer Method, where every projection is tested against market data and the legal position before a buyer commits. Through Fullers Private Office and Fullers Wealth Club, launching shortly in Singapore, we bring the same discipline to private investors and family offices looking for a second home in Indonesia that also earns its place in a portfolio.
The bond on that conference screen sets the bar. The right Bali villa clears it on income, holds its value through a properly structured lease, and gives its owners something the bond never will. Those villas exist. Finding them, verifying them and negotiating for them is what our Private Office and advisory teams do every day. What separates the villas returning 15 per cent and more from everything else is a subject I will return to in this column.